EM debt has remained resilient despite the U.S.-Iran conflict, as energy-market disruption has been less severe than feared.
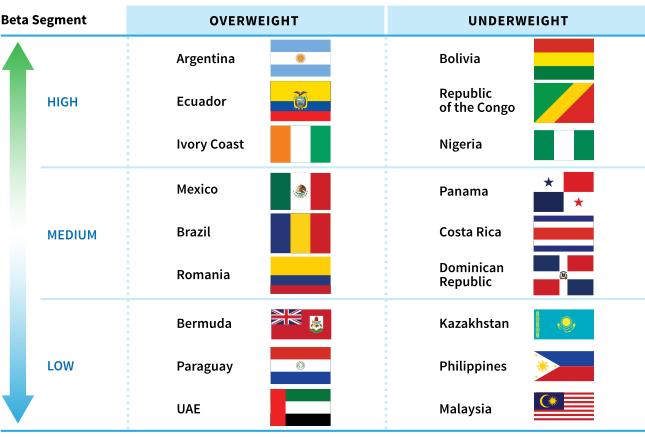
In high- and medium-beta markets, we favor credits such as Argentina, Brazil, Romania, and Ivory Coast, where valuations appear attractive relative to perceived risks in our view.
In lower-beta markets, we are more selective, preferring credits such as Bermuda, Paraguay, and the UAE to Kazakhstan, the Philippines, and Malaysia, where we believe spreads appear too tight.
Emerging markets (EMs) have held up well despite repeated escalation and de-escalation in the U.S.-Iran conflict. The disruptions around the Strait of Hormuz have driven up energy prices, made them more volatile, and put inflation and monetary policy back in focus. But the shock has been less severe than feared: EM growth remains resilient and inflation contained. Middle East oil exports have recovered to roughly 70% to 80% of prewar volumes despite the partial closure of the Strait, and China tapped reserves and cut imports in response to higher prices, easing demand.
We continue to monitor geopolitical tensions, as further escalation of the U.S.-Iran conflict, including attacks on re-routed shipping, could easily send energy prices higher.
Meanwhile, we’re staying on top of volatility in developed-market government bonds, which have been driven by elevated fiscal and debt trajectories and anticipation of additional monetary policy action. However, the market may already be overestimating this risk, given how well EM economies and markets have held up so far.
Overall, we remain constructive on EM debt as we move into 2027. Volatility may continue given the geopolitical and macroeconomic backdrop, but we believe the asset class benefits from resilient fundamentals, supportive technicals, and attractive absolute yields.
That said, in our view, the environment favors a selective approach, with opportunities in both hard and local currency markets for active investors.
Below, we break down some of our largest active hard-currency positions in each beta bucket.
Beta-Bucket Approach: Select Active Positions
To allocate capital and budget risk effectively across a large and diverse set of countries, we use a proprietary grouping framework.
Rather than organizing by region, we classify issuers into low-, medium-, and high‑beta buckets. We believe this approach captures true risk profiles given the wide range of development levels within regions and allows for fairer comparisons and more optimal portfolio construction.
Risk budgets are allocated dynamically: when our top‑down scores are more positive, we increase exposure to high‑beta countries. Portfolio‑level exposure is monitored and adjusted continuously to maintain an optimal risk/return balance.
Source: William Blair, as of September 2026. Beta buckets are based on the team’s qualitative and quantitative analysis. Risk buckets are provided for illustrative purposes only and are not intended as investment advice or as projections of future returns. Overweights/underweights may vary between vehicles.
High-Beta Bucket
In high-beta markets, we are selectively embracing risk where we feel improving fundamentals and attractive valuations outweigh political or policy uncertainty, while avoiding credits where downside risks remain insufficiently compensated.
Argentina (overweight): Electoral jitters have caused bonds to sell off, and we are monitoring the election closely, but we are optimistic. We believe Argentina remains on a positive fundamental trajectory as fiscal discipline and reserve accumulation by the central bank continue.
Ecuador (overweight): Although fundamental challenges have increased due to an upcoming local election and concerns over El Niño’s impact on the electricity sector, we believe longer-duration bonds offer attractive risk-adjusted returns.
Ivory Coast (overweight): The euro-denominated 2048 bond provides long spread-duration exposure to strong growth, improving debt dynamics, and increasing hydrocarbon and gold production. Limited external issuance and demand for higher-quality African credit remain supportive, although strong euro-curve performance has reduced some of the earlier valuation advantage.
Bolivia (underweight): We are concerned about the country’s fundamental trajectory. A significant adjustment is needed, and we do not believe bonds currently compensate investors for the risks.
Republic of the Congo (underweight): We are concerned about high debt, recurrent arrears, and weak debt administration. Although higher oil prices and liability-management operations have reduced near-term refinancing pressure, we believe recent market-access gains leave valuations insufficiently attractive relative to peers.
Nigeria (underweight): Stronger external balances, higher reserves, and continued reform have improved Nigeria’s credit profile, but this progress is increasingly reflected in tight sovereign spreads. Persistent fiscal weaknesses, including low revenue mobilization, high debt-service costs, and the prospect of external issuance by Nigeria support maintaining an underweight in sovereign spread duration while retaining selective corporate exposure.
Medium-Beta Bucket
In medium-beta markets, relative value is the key differentiator: we favor credits where spreads appear to overstate fundamental risks and remain cautious where strong performance has left valuations less compelling.
Mexico (overweight): We remain overweight Pemex, which we believe is well supported by the sovereign and offers attractive valuations relative to sovereign bonds; the Mexican sovereign, which we believe has an attractive valuation. We also have corporate bond positions in utilities and financials.
Brazil (overweight): We increased duration ahead of the elections, as we believed bond markets were overly penalizing Brazil for the risks. The curve is steep, and creditworthiness remains high given the country’s large international reserves and low level of dollar-denominated debt.
While challenges remain in Romania, we expect continued progress.
Romania (overweight): We believe spreads continue to overstate the risks associated with the country’s fiscal and political adjustment process. While challenges remain, we expect continued progress on fiscal consolidation and ongoing support from European institutions, leaving valuations attractive relative to peers.
Panama (underweight): Although the outlook for the mine reopening looks positive, we believe valuations are too tight as bonds have rallied.
Costa Rica (underweight): We believe sovereign bonds are unattractively valued, although we acknowledge the country is on a positive fundamental trajectory.
Dominican Republic (underweight): Despite recent fiscal reform approval, resilient economic growth, and tourism numbers, valuations are not appealing.
Low-Beta Bucket
In low-beta markets, we are focused on high-quality credits that still offer attractive carry or relative value, while underweighting markets where strong fundamentals are already fully reflected in tight spreads.
Bermuda (overweight): We hold an off-benchmark, low-beta position given its high single-A credit quality and attractive valuations.
Paraguay (overweight): We find valuations attractive relative to low-beta peers and solid fundamentals. Although there has been some fiscal slippage recently, the country’s debt-to-gross-domestic-product (GDP) ratio remains low, and Paraguay has a strong track record of low fiscal deficits.
Despite periodic volatility related to regional geopolitical developments, we are overweight UAE.
United Arab Emirates (overweight): Despite periodic volatility related to regional geopolitical developments, we believe spreads continue to offer attractive relative value and carry.
Kazakhstan (underweight): We believe strong investment-grade fundamentals are already reflected in tight sovereign and quasi-sovereign spreads. In our view, limited relative value, prospective new issuance, and residual risks around the Caspian Pipeline Consortium (CPC) oil-export route leave insufficient compensation for matching the benchmark’s duration, so we maintain only selective exposure.
Philippines (underweight): Valuations are tight and we expect further fundamental deterioration, with exceptionally high inflation risks stemming from the oil shock, elevated rice prices, flooding, and El Niño likely to drive a sharp deceleration in growth.
Malaysia (underweight): While we have select overweight exposure to quasi-sovereign bonds offering attractive valuations relative to the sovereign bonds included in the index, we are underweight sovereign bonds themselves due to tight valuations.
Marco Ruijer, CFA, is a portfolio manager on William Blair’s emerging markets debt team.
Subscribe Now
Want the latest insights on the economy and other forces shaping the investment landscape?
Subscribe to our Investing Insights newsletter.
Any investment or strategy mentioned herein may not be appropriate for every investor. There can be no assurance that investment objectives will be met. Products and services listed are available only to residents of this jurisdiction and may only be available to certain categories of investors. The information on this website does not constitute an offer for products or services, or a solicitation of an offer to any persons outside of this jurisdiction who are prohibited from receiving such information under applicable laws and regulations. Nothing on this webpage should be construed as advice and is therefore not a recommendation to buy or sell shares.
Please carefully consider the Funds’ investment objectives, risks, charges, and expenses before investing. This and other information is contained in the Funds’ prospectus and summary prospectus, which you may obtain by calling 1-800-742-7272. Read the prospectus and summary prospectus carefully before investing. Investing includes the risk of loss.
The William Blair Funds and William Blair ETFs are distributed by William Blair & Company, L.L.C., member FINRA/SIPC.
The William Blair SICAV is a Luxembourg investment company with variable capital registered with the Commission de Surveillance du Secteur Financier (“CSSF”) which qualifies as an undertaking for collective investment in transferable securities (“UCITS”). The Management Company of the SICAV has appointed William Blair Investment Management, LLC as the investment manager for the fund.
Please carefully consider the investment objectives, risks, charges, and expenses of the William Blair SICAV. This and other important information is contained in the prospectus and Key Investor Information Document (KIID). Read these documents carefully before investing. The information contained on this website is not a substitute for those documents or for professional external advice.
Information and opinions expressed are those of the authors and may not reflect the opinions of other investment teams within William Blair Investment Management, LLC, or affiliates. Factual information has been taken from sources we believe to be reliable, but its accuracy, completeness or interpretation cannot be guaranteed. Information is current as of the date appearing in this material only and subject to change without notice. Statements concerning financial market trends are based on current market conditions, which will fluctuate. This material may include estimates, outlooks, projections, and other forward-looking statements. Due to a variety of factors, actual events may differ significantly from those presented.
Investing involves risks, including the possible loss of principal. Equity securities may decline in value due to both real and perceived general market, economic, and industry conditions. The securities of smaller companies may be more volatile and less liquid than securities of larger companies. Investing in foreign denominated and/or domiciled securities may involve heightened risk due to currency fluctuations, and economic and political risks. These risks may be enhanced in emerging markets and frontier markets. Investing in the bond market is subject to certain risks including market, interest rate, issuer, credit, and inflation risk. High-yield, lower-rated, securities involve greater risk than higher-rated securities. Different investment styles may shift in and out of favor depending on market conditions. Diversification does not ensure against loss.
Past performance is not indicative of future returns. References to specific companies are for illustrative purposes only and should not be construed as investment advice or a recommendation to buy or sell any security.
William Blair Investment Management, LLC is an investment adviser registered with the U.S. Securities and Exchange Commission.
Issued in the United Kingdom by William Blair International, Ltd., authorized and regulated by the Financial Conduct Authority (FCA), and is only directed at and is only made available to persons falling within articles 19, 38, 47, and 49 of the Financial Services and Markets Act of 2000 (Financial Promotion) Order 2005 (all such persons being referred to as "relevant persons").
Issued in the European Economic Area (EEA) by William Blair B.V., authorized and supervised by the Dutch Authority for the Financial Markets (AFM) under license number 14006134 and also supervised by the Dutch Central Bank (DNB), registered at the Dutch Chamber of Commerce under number 82375682 and has its statutory seat in Amsterdam, the Netherlands. This material is only intended for eligible counterparties and professional clients.
Issued in Switzerland by William Blair Investment Services (Zurich) GmbH, Talstrasse 65, 8001 Zurich, Switzerland ("WBIS"). WBIS is engaged in the offering of collective investment schemes and renders further, non-regulated services in the financial sector. WBIS is affiliated with FINOS Finanzomubdsstelle Schweiz, a recognized ombudsman office where clients may initiate mediation proceedings pursuant to articles 74 et seq. of the Swiss Financial Services Act ("FinSA"). The client advisers of WBIS are registered with regservices.ch by BX Swiss AG, a client adviser registration body authorized by the Swiss Financial Market Supervisory Authority ("FINMA"). WBIS is not supervised by FINMA or any other supervisory authority or self-regulatory organization. This material is only intended for institutional and professional clients pursuant to article 4(3) to (5) FinSA.
Issued in Australia by William Blair Investment Management, LLC (“William Blair”), which is exempt from the requirement to hold an Australian financial services license under Australia's Corporations Act 2001 (Cth). William Blair is registered as an investment advisor with the U.S. Securities and Exchange Commission (“SEC”) and regulated by the SEC under the U.S. Investment Advisers Act of 1940, which differs from Australian laws. This material is intended only for wholesale clients.
Issued in Singapore by William Blair International (Singapore) Pte. Ltd. (Registration Number 201943312R), which is regulated by the Monetary Authority of Singapore under a Capital Markets Services License to conduct fund management activities. This material is intended only for institutional investors and may not be distributed to retail investors.
Issued in Canada by William Blair Investment Management, LLC, which relies on the international adviser exemption, pursuant to section 8.26 of National Instrument 31-103 in Canada.
The content contained in this site is intended as informational or educational in nature and does not constitute investment advice or a recommendation of any investment strategy or product for a particular investor. Investment advice and recommendations can be provided only after careful consideration of an investor’s objectives, guidelines, and restrictions. Investors should consult a financial professional/financial consultant or investment adviser before making any investment decisions. Investing includes the risk of loss.