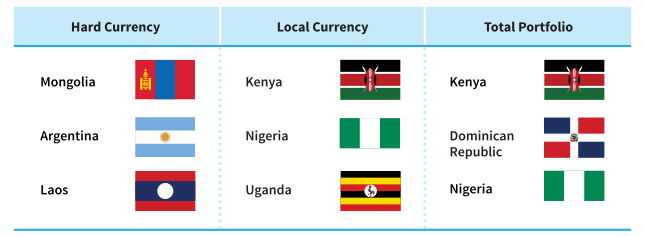
Our top hard-currency exposures are Mongolia, Argentina, and Laos.
Our top local-currency exposures are Kenya, Nigeria, and Uganda.
We believe frontier still looks attractive, but after a strong past year, we expect future returns to come from carry and selectivity rather than broad market gains.
We believe frontier debt presents an attractive investment opportunity, supported by resilient fundamentals, high real yields, and improving policy credibility across a number of markets. But after significant spread compression and monetary easing over the past year, we believe the next phase of returns will be driven less by broad market beta and more by carry, country selection, and security selection.
That makes selectivity increasingly important. Scope for further rate cuts remains in markets such as Egypt, Zambia, Kazakhstan, and Kenya as inflation moderates and external balances improve, while easing in Nigeria is likely to be more gradual.
At the same time, tighter credit spreads, more concentrated positioning, and continued volatility in developed market rates argue against a broad-based approach.
Even so, absolute yields remain compelling relative to mainstream emerging markets and developed market sovereign debt, preserving what we believe is a meaningful yield and diversification premium.
Against this backdrop, we remain constructive on frontier debt as we move into 2027, while closely monitoring geopolitical risks and volatility in developed market bond markets.
Below, we highlight the portfolio’s largest exposures across hard currency, local currency, and the overall portfolio.
Top Exposures
Source: William Blair, as of September 2026.
Hard Currency Positions
Our top hard-currency exposures are Mongolia, Argentina, and Laos.
Mongolia: Mongolia is a commodity and energy exporter, with coal and energy revenues providing external buffers, and its fundamentals continue to improve.
Argentina: Electoral jitters ahead of next year’s elections have weighed on the bonds, but we believe Argentina is on a positive fundamental trajectory as fiscal discipline and reserve accumulation by the central bank continue.
Laos: We believe the combination of strong carry, improving macroeconomic conditions, and limited duration risk provides an attractive risk-adjusted return profile.
Local Currency Positions
Our top local-currency exposures are Kenya, Nigeria, and Uganda.
Kenya: Inflation remains relatively well contained and external balances have improved meaningfully over the past two years, supporting a more stable macroeconomic backdrop.
Nigeria: High local interest rates, improved FX liquidity, and continued policy reform momentum support the naira. While positioning has become more crowded over time, we continue to believe that attractive carry, stronger investor confidence, and improving macroeconomic fundamentals provide support for further positive returns.
Uganda: We remain constructive on local rates, supported by well-contained inflation, solid external buffers, and stable macroeconomic management. The country also continues to benefit from oil-sector-related investment flows, while policy continuity reinforces our favorable outlook.
Total Portfolio Positions
Our top total exposures are Kenya, Dominican Republic, and Nigeria.
Dominican Republic: Strong external accounts are underpinned by robust tourism revenues, remittances, and foreign direct investment (FDI) inflows. International reserves remain healthy, while balance-of-payments dynamics have been supportive of currency stability. The Dominican Republic also has solid economic growth and continued access to international capital markets.
Nigeria: Nigeria’s outlook continues to improve, supported by stronger external balances, higher reserves, improved foreign exchange liquidity, and continued reform momentum. High local interest rates and greater investor confidence also remain supportive, particularly for the naira. However, fiscal challenges persist, including low revenue mobilization and high debt-service costs, while much of the improvement in the credit profile is increasingly reflected in tight sovereign spreads. Overall, we believe improving fundamentals remain supportive, although valuations warrant selectivity.
Yvette Babb is a portfolio manager on William Blair’s emerging markets debt team.
Daniel Wood is a portfolio manager on William Blair’s emerging markets debt team.
Want the latest insights on the economy and other forces shaping the investment landscape?
Subscribe to our Investing Insights newsletter.
Any investment or strategy mentioned herein may not be appropriate for every investor. There can be no assurance that investment objectives will be met. Products and services listed are available only to residents of this jurisdiction and may only be available to certain categories of investors. The information on this website does not constitute an offer for products or services, or a solicitation of an offer to any persons outside of this jurisdiction who are prohibited from receiving such information under applicable laws and regulations. Nothing on this webpage should be construed as advice and is therefore not a recommendation to buy or sell shares.
Please carefully consider the Funds’ investment objectives, risks, charges, and expenses before investing. This and other information is contained in the Funds’ prospectus and summary prospectus, which you may obtain by calling 1-800-742-7272. Read the prospectus and summary prospectus carefully before investing. Investing includes the risk of loss.
The William Blair Funds and William Blair ETFs are distributed by William Blair & Company, L.L.C., member FINRA/SIPC.
The William Blair SICAV is a Luxembourg investment company with variable capital registered with the Commission de Surveillance du Secteur Financier (“CSSF”) which qualifies as an undertaking for collective investment in transferable securities (“UCITS”). The Management Company of the SICAV has appointed William Blair Investment Management, LLC as the investment manager for the fund.
Please carefully consider the investment objectives, risks, charges, and expenses of the William Blair SICAV. This and other important information is contained in the prospectus and Key Investor Information Document (KIID). Read these documents carefully before investing. The information contained on this website is not a substitute for those documents or for professional external advice.
Information and opinions expressed are those of the authors and may not reflect the opinions of other investment teams within William Blair Investment Management, LLC, or affiliates. Factual information has been taken from sources we believe to be reliable, but its accuracy, completeness or interpretation cannot be guaranteed. Information is current as of the date appearing in this material only and subject to change without notice. Statements concerning financial market trends are based on current market conditions, which will fluctuate. This material may include estimates, outlooks, projections, and other forward-looking statements. Due to a variety of factors, actual events may differ significantly from those presented.
Investing involves risks, including the possible loss of principal. Equity securities may decline in value due to both real and perceived general market, economic, and industry conditions. The securities of smaller companies may be more volatile and less liquid than securities of larger companies. Investing in foreign denominated and/or domiciled securities may involve heightened risk due to currency fluctuations, and economic and political risks. These risks may be enhanced in emerging markets and frontier markets. Investing in the bond market is subject to certain risks including market, interest rate, issuer, credit, and inflation risk. High-yield, lower-rated, securities involve greater risk than higher-rated securities. Different investment styles may shift in and out of favor depending on market conditions. Diversification does not ensure against loss.
Past performance is not indicative of future returns. References to specific companies are for illustrative purposes only and should not be construed as investment advice or a recommendation to buy or sell any security.
William Blair Investment Management, LLC is an investment adviser registered with the U.S. Securities and Exchange Commission.
Issued in the United Kingdom by William Blair International, Ltd., authorized and regulated by the Financial Conduct Authority (FCA), and is only directed at and is only made available to persons falling within articles 19, 38, 47, and 49 of the Financial Services and Markets Act of 2000 (Financial Promotion) Order 2005 (all such persons being referred to as "relevant persons").
Issued in the European Economic Area (EEA) by William Blair B.V., authorized and supervised by the Dutch Authority for the Financial Markets (AFM) under license number 14006134 and also supervised by the Dutch Central Bank (DNB), registered at the Dutch Chamber of Commerce under number 82375682 and has its statutory seat in Amsterdam, the Netherlands. This material is only intended for eligible counterparties and professional clients.
Issued in Switzerland by William Blair Investment Services (Zurich) GmbH, Talstrasse 65, 8001 Zurich, Switzerland ("WBIS"). WBIS is engaged in the offering of collective investment schemes and renders further, non-regulated services in the financial sector. WBIS is affiliated with FINOS Finanzomubdsstelle Schweiz, a recognized ombudsman office where clients may initiate mediation proceedings pursuant to articles 74 et seq. of the Swiss Financial Services Act ("FinSA"). The client advisers of WBIS are registered with regservices.ch by BX Swiss AG, a client adviser registration body authorized by the Swiss Financial Market Supervisory Authority ("FINMA"). WBIS is not supervised by FINMA or any other supervisory authority or self-regulatory organization. This material is only intended for institutional and professional clients pursuant to article 4(3) to (5) FinSA.
Issued in Australia by William Blair Investment Management, LLC (“William Blair”), which is exempt from the requirement to hold an Australian financial services license under Australia's Corporations Act 2001 (Cth). William Blair is registered as an investment advisor with the U.S. Securities and Exchange Commission (“SEC”) and regulated by the SEC under the U.S. Investment Advisers Act of 1940, which differs from Australian laws. This material is intended only for wholesale clients.
Issued in Singapore by William Blair International (Singapore) Pte. Ltd. (Registration Number 201943312R), which is regulated by the Monetary Authority of Singapore under a Capital Markets Services License to conduct fund management activities. This material is intended only for institutional investors and may not be distributed to retail investors.
Issued in Canada by William Blair Investment Management, LLC, which relies on the international adviser exemption, pursuant to section 8.26 of National Instrument 31-103 in Canada.
The content contained in this site is intended as informational or educational in nature and does not constitute investment advice or a recommendation of any investment strategy or product for a particular investor. Investment advice and recommendations can be provided only after careful consideration of an investor’s objectives, guidelines, and restrictions. Investors should consult a financial professional/financial consultant or investment adviser before making any investment decisions. Investing includes the risk of loss.